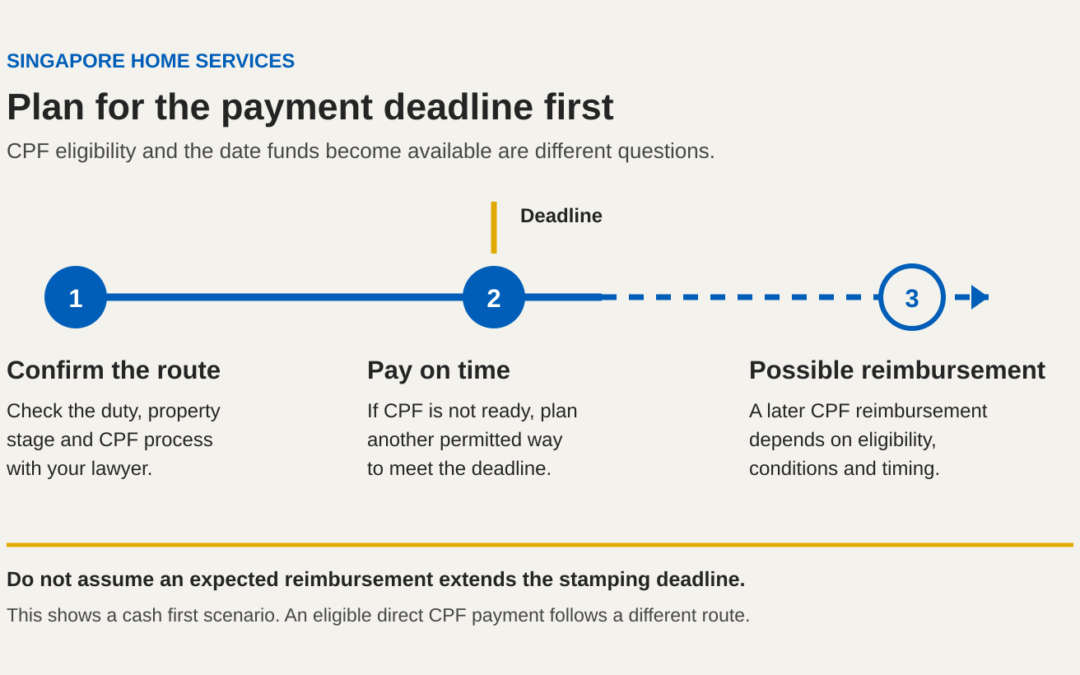
Plan for stamp duty as an early cash requirement, even if you intend to use CPF savings eventually. CPF eligibility and the date money becomes available are separate questions. Confirm both before committing to a purchase.
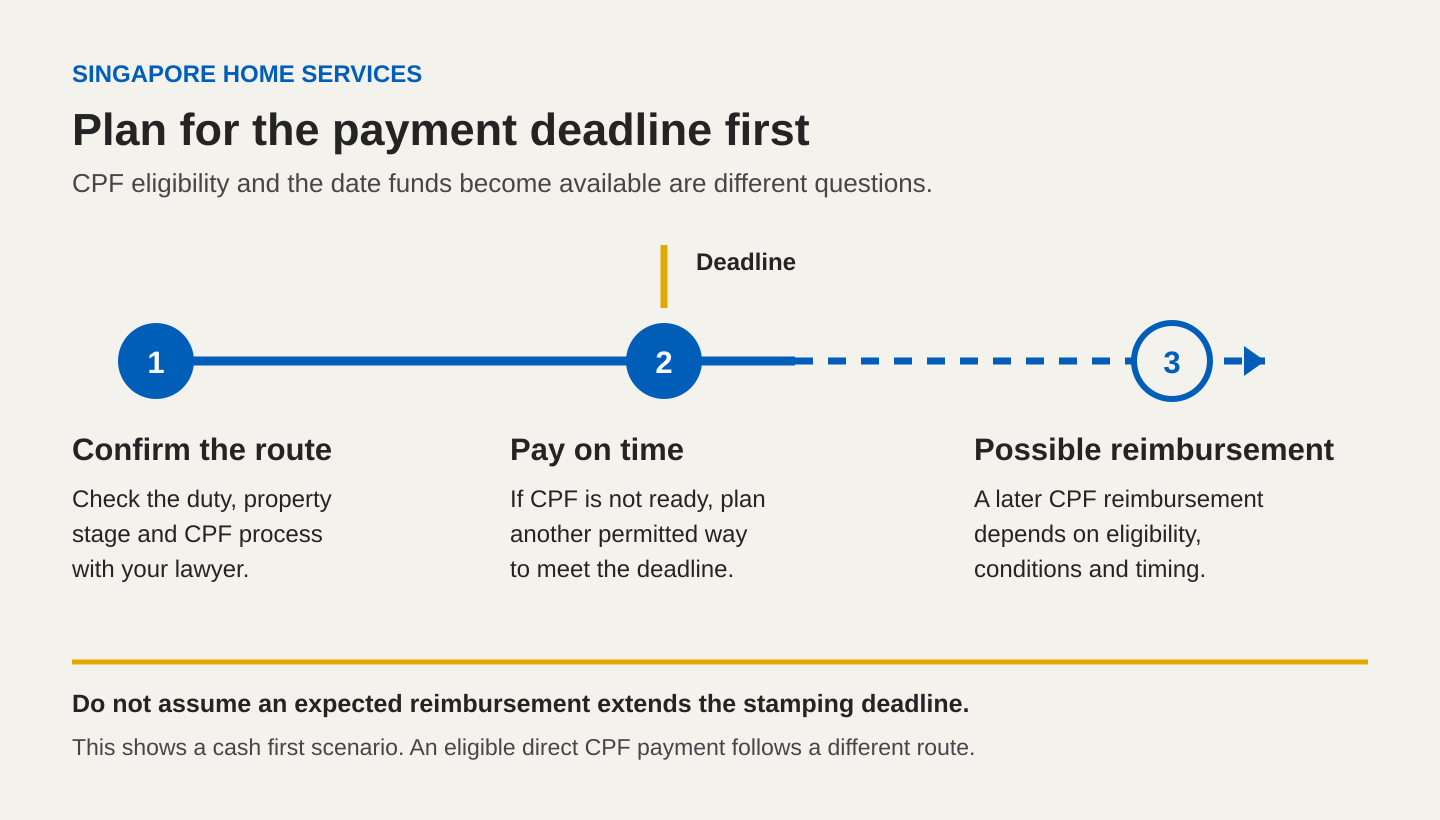
CPF Board says buyers generally pay stamp duty in cash first, then apply for reimbursement when a CPF charge can be lodged. That charge secures the required CPF refund when the property is sold or disposed of. CPF guidance on property-related fees
A useful purchase budget therefore has two views: your total funding and the cash available on each payment date. A comfortable CPF balance does not, by itself, answer the second question.
Information checked on 11 November 2026. This guide supports cash-flow planning; confirm your transaction’s duties and CPF arrangements with your conveyancing lawyer, CPF Board or HDB.
Put the stamp duty deadline on your calendar first
IRAS says documents should be stamped before signing. Its normal penalty-free windows after signing are:
- Signed in Singapore: within 14 days after signing.
- Signed overseas: within 30 days after the document is received in Singapore.
Signing generally means the first signature. Electronic documents have specific execution and receipt rules, so ask your lawyer which date starts your deadline. Do not automatically count from collecting the keys. IRAS payment deadlines
Dated exception: IRAS currently extends stamping and payment deadlines falling on 22–28 December 2026 to 5 January 2027 because of its portal enhancements. This is a specific exception, not a general extension. Recheck it if your transaction falls in that period. IRAS December deadline extension
Check which CPF payment route applies
The property’s status matters. OA below means your CPF Ordinary Account:
On a small screen, scroll the table sideways to see every column.
| Purchase situation | CPF Board’s stated position |
|---|---|
| Completed property | Apply with the lump-sum drawdown before legal completion; reimbursement is processed only on completion. OA cannot fund stamp duty beforehand. |
| Property under construction | Apply for reimbursement on or before completion. Direct OA payment may be possible if charge documentation and lodgment finish within 14 days. |
| HDB loan applicant | Verify reimbursement eligibility with HDB. |
| Developer has already paid the duty | CPF reimbursement is unavailable. |
Source: CPF Board’s payment and reimbursement guidance.
Do not put an assumed reimbursement date into your budget. Ask who submits the request, what documents they need and when the money can realistically be available to you.
Work out the duty separately from the deposit
Buyer’s Stamp Duty (BSD) uses the higher of the purchase price and market value, not the mortgage amount or cash deposit. For residential acquisitions from 15 February 2023, the first three bands are 1% on S$180,000, 2% on the next S$180,000 and 3% on the next S$640,000. IRAS BSD rules and rates
For a hypothetical home with both price and market value of S$1 million:
On a small screen, scroll the table sideways to see every column.
| Portion of value | Calculation | BSD |
|---|---|---|
| First S$180,000 | S$180,000 × 1% | S$1,800 |
| Next S$180,000 | S$180,000 × 2% | S$3,600 |
| Remaining S$640,000 | S$640,000 × 3% | S$19,200 |
| Total | S$24,600 |
This is a BSD-only illustration. It excludes ABSD, legal fees, mortgage duty, all other costs and financing.
Suppose you have S$35,000 of cash left after setting aside the deposit and other already-budgeted commitments. Paying S$24,600 leaves S$10,400. That is the amount to test against your remaining bills and emergency reserve before any reimbursement arrives.
The example does not establish that S$35,000 is sufficient to buy the property.
Keep ABSD separate from an expected refund
Additional Buyer’s Stamp Duty (ABSD), where applicable, is payable on top of BSD. Liability depends on the buyer’s profile at purchase, including residency and residential-property ownership.
IRAS says stamp duty must be paid in full and cannot be deferred because funds are insufficient. An expected ABSD refund should not be entered as cash available for the original payment. Confirm any remission or refund conditions separately rather than assuming a future sale makes you eligible. IRAS ABSD guidance
Build a cash plan for each payment
Use a worksheet like this before signing. The checks below are practical planning steps, not additional regulatory requirements.
On a small screen, scroll the table sideways to see every column.
| Stage | What to record | What to confirm |
|---|---|---|
| Before committing | Accessible cash, planned deposits and protected emergency reserve | Whether cash remains sufficient after each early payment |
| Before the duty deadline | BSD, any ABSD, funding account and payment date | Your lawyer’s calculation, payment instructions and transfer limits |
| Before CPF submission | Amount requested and supporting records | Eligibility, submission responsibility and missing paperwork |
| Before completion | Remaining cash obligations and expected CPF movements | Whether the same OA savings have been allocated twice |
| After payment and reimbursement | Actual amounts and dates | Reconcile records before using released cash for renovations or furnishings |
Keep two separate columns for “cash available now” and “expected reimbursement”. Do not total them together when checking whether you can meet an earlier deadline.
For the wider purchase budget, SHS’s new home loan guide provides the financing context. Buyers considering a condominium or landed home can also review private-property financing considerations.
Your checklist before signing
- Obtain a transaction-specific BSD and ABSD calculation.
- Record the actual stamping deadline and any applicable exception.
- Confirm the payment route before relying on CPF.
- Check available OA savings after other planned housing uses.
- Leave a cash buffer for costs whose final amounts are not yet confirmed.
- Keep payment evidence and ask which reimbursement records are required.
CPF housing eligibility can depend on the remaining lease, property and loan type, and whether this is a subsequent property. Stamp duty and legal fees are excluded from the CPF housing limit, but that does not establish your available OA balance or individual eligibility. Use the CPF Housing Usage Calculator alongside CPF’s eligibility guidance.
Common questions
Is CPF reimbursement the same as an IRAS tax refund?
No. Reimbursement concerns how an eligible expense is funded from CPF. An IRAS remission or refund concerns the tax treatment. Track them separately and verify each set of conditions.
Does a smaller mortgage reduce BSD?
Not by itself. BSD is calculated from the higher of price and market value. Changing your borrowing does not change that calculation.
What should I do if the early cash requirement is too high?
Review the purchase budget and funding sequence before committing. Ask your lawyer which amounts are due when, then assess what you can fund without relying on an unconfirmed reimbursement or refund.
Plan the mortgage alongside the cash timeline
SHS helps buyers compare home-loan packages across multiple banks. Request a mortgage comparison with your property type and estimated loan amount, and flag any early cash-flow constraint. Eligibility, pricing and approval remain subject to the selected bank’s assessment.